Tracing the Novelty,
Savoring the Future
A survey of 1,030 Nanjing residents on willingness to buy novelty-flavored beverages — modeled with the Theory of Planned Behavior, K-means clustering and SEM.
When weird flavors go viral
From salted-egg-yolk soda to cilantro juice, novelty flavors have become the beverage industry's most talked-about frontier — but virality does not guarantee repeat purchase.
Beverage GMV on major e-commerce platforms, Jan–Jul 2024 +27.8% YoY
Quarterly sales growth of niche flavors (cilantro, houttuynia, luosifen, durian) on Taobao, Q1 2024
Online orders of Huiyuan 100% cilantro juice within its first week — despite polarized reviews
“Why do consumers pay for novelty-flavored beverages — and how does the decision logic systematically differ across consumer groups?”
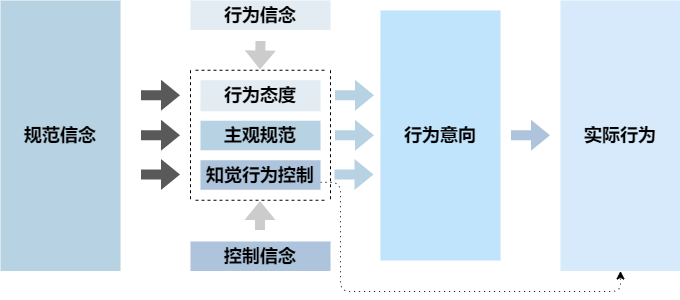
The TPB engine, made clickable
The questionnaire operationalizes the Theory of Planned Behavior across four constructs, five Likert items each. Select a node to inspect its definition, sample items and evidence.
From questionnaire to model
A multi-stage sampling design across six Nanjing districts, followed by a full statistical pipeline in SPSS and AMOS.
Instrument design
TPB-based questionnaire; 4 constructs × 5 Likert items, refined through an 87-response pilot.
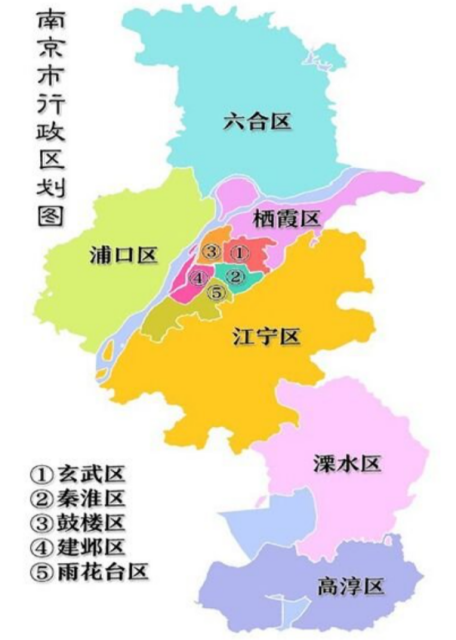
Multi-stage sampling
Stratified + Lahiri + SRS; six districts — Lishui, Jiangning, Qinhuai, Jianye, Qixia, Luhe.
Fieldwork
Online + offline interception surveys in public spaces; dual data entry and four validity screens.
Analysis
SPSS + AMOS: reliability & validity, EFA, ordered-logistic regression, K-means, MANOVA, SEM.
What 1,030 residents told us
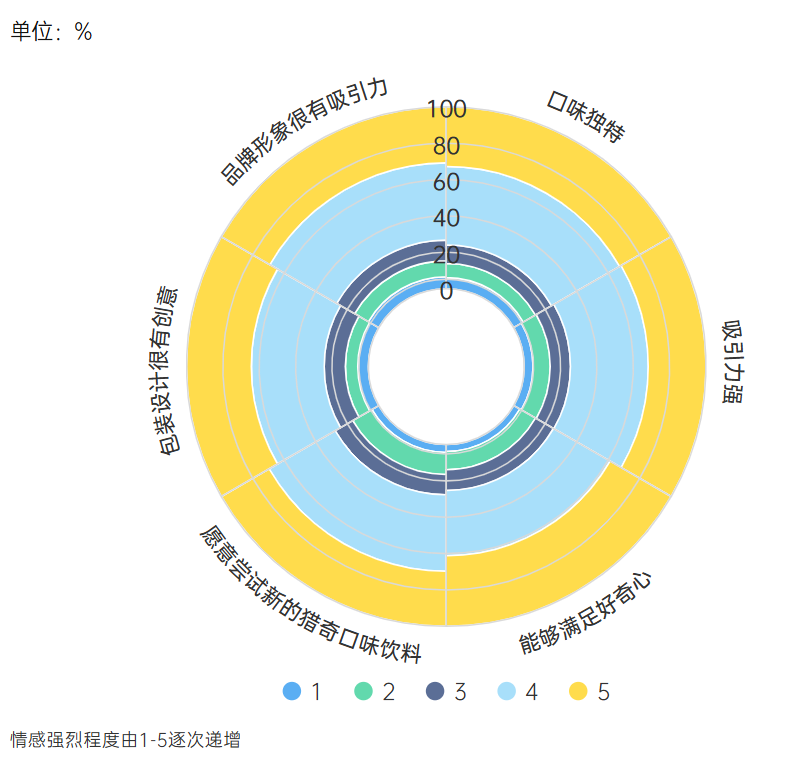
Social influence runs high, purchase conditions are favorable — yet conversion lags far behind intention.
Subjective norm — % agreement
Perceived behavioral control — means
Purchase intention — means
Monthly disposable income
Three tribes of novelty drinkers
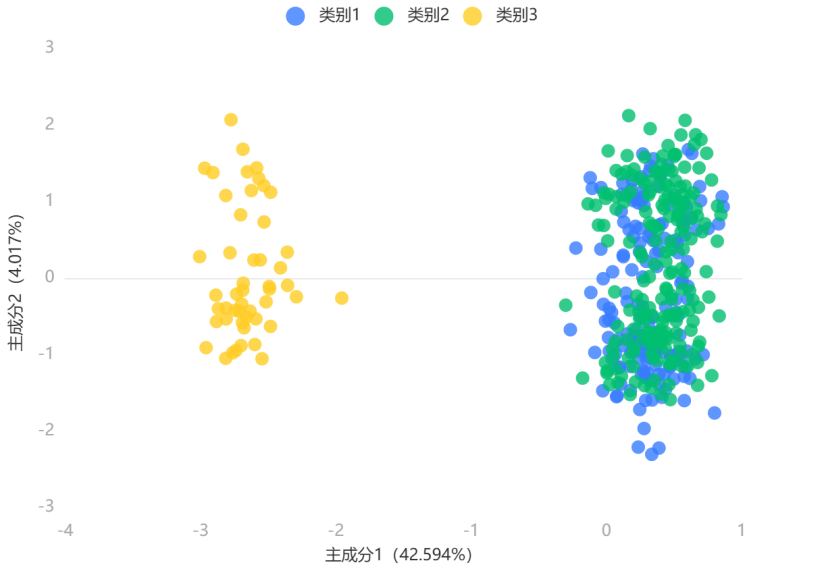
K-means clustering (elbow method, silhouette 0.389) separates consumers into three sharply distinct groups.
The social-driven core
- Mid income & education; high liking and trial intent
- Highly swayed by friends, family and social media
- The core growth audience for novelty launches
The quality-led potential
- Higher education & income; uniqueness and brand image matter
- Decisions still driven by family and social circles
- Natural target for premium, design-led lines
The hesitant minority
- Younger, lower income; interest and intent far below others
- Low scores on attitude, norm and control alike
- Not a priority segment for current campaigns
Segment share of sample
Attitude & trial intent by segment
The model holds — and explains
All six hypothesized paths are significant and positive. Attitude is the strongest direct driver of intention, followed by subjective norm and perceived control.
Four takeaways, one playbook
Novelty beverages are bought socially, judged on experience, and lost at the last mile.
Subjective norms dominate
Novelty & convenience convert
The intention–behavior gap
Health & function emerge
For brands
For consumers
Check ingredients & certifications Start with small packs Brand over flashy packaging Convenience & fair priceSurvey instruments & paper artifacts
Novelty-Flavored Beverage Consumption Survey
Section A · Attitude toward novelty beverages 行为态度
| Item 题项 | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| High overall liking for novelty beverages我对猎奇口味饮料的整体喜好程度很高 | ○ | ○ | ○ | ○ | ○ |
| The taste is truly unique猎奇口味饮料的口味非常独特 | ○ | ○ | ○ | ○ | ○ |
| More appealing than regular beverages猎奇口味饮料比普通饮料更有吸引力 | ○ | ○ | ○ | ○ | ○ |
| Satisfies my curiosity猎奇口味饮料能够满足我的好奇心 | ○ | ○ | ○ | ○ | ○ |
| Very willing to try new novelty flavors我非常愿意尝试新的猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| The packaging design is creative猎奇口味饮料的包装设计很有创意 | ○ | ○ | ○ | ○ | ○ |
| The brand image attracts me猎奇口味饮料的品牌形象很吸引我 | ○ | ○ | ○ | ○ | ○ |
Section B · Subjective norm 主观规范
| Item 题项 | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| My family strongly supports my purchase我的家人非常支持我购买猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Friends often recommend them to me我的朋友经常推荐我购买猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Others' opinions change my purchase decisions我会因为周围人的意见而改变购买决策 | ○ | ○ | ○ | ○ | ○ |
| I feel everyone around me is buying them我觉得周围人都在购买猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Buying them is a trendy behavior购买猎奇口味饮料是一种潮流行为 | ○ | ○ | ○ | ○ | ○ |
| My colleagues rate them highly我的同事对猎奇口味饮料的评价很高 | ○ | ○ | ○ | ○ | ○ |
| I refer to social media recommendations我会参考社交媒体上的相关推荐 | ○ | ○ | ○ | ○ | ○ |
Section C · Perceived behavioral control 感知行为控制
| Item 题项 | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Buying them is very convenient购买猎奇口味饮料非常方便 | ○ | ○ | ○ | ○ | ○ |
| The price is reasonable猎奇口味饮料的价格非常合理 | ○ | ○ | ○ | ○ | ○ |
| I encounter almost no barriers购买时几乎不会遇到障碍 | ○ | ○ | ○ | ○ | ○ |
| Sales channels are abundant猎奇口味饮料的销售渠道非常多 | ○ | ○ | ○ | ○ | ○ |
| Packaging strongly influences my decision包装设计对我的购买决策影响非常大 | ○ | ○ | ○ | ○ | ○ |
| Easy to find in supermarkets我很容易在超市找到猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Promotions attract me猎奇口味饮料的促销活动很吸引我 | ○ | ○ | ○ | ○ | ○ |
Section D · Purchase intention 购买意图
| Item 题项 | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| I will definitely buy in the future我未来一定会购买猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Very willing to recommend to others我非常愿意向他人推荐猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Plan to buy within a month我计划在未来一个月内购买猎奇口味饮料 | ○ | ○ | ○ | ○ | ○ |
| Buying them is a fun experience购买猎奇口味饮料是一种非常有趣的体验 | ○ | ○ | ○ | ○ | ○ |
| A product well worth trying猎奇口味饮料是一种非常值得尝试的产品 | ○ | ○ | ○ | ○ | ○ |
| I regularly follow new launches我会定期关注猎奇口味饮料的新品信息 | ○ | ○ | ○ | ○ | ○ |
| Promotions increase my purchase volume我会因为优惠活动而增加购买量 | ○ | ○ | ○ | ○ | ○ |
Open questions 开放题
Research framework — original figure from the paper
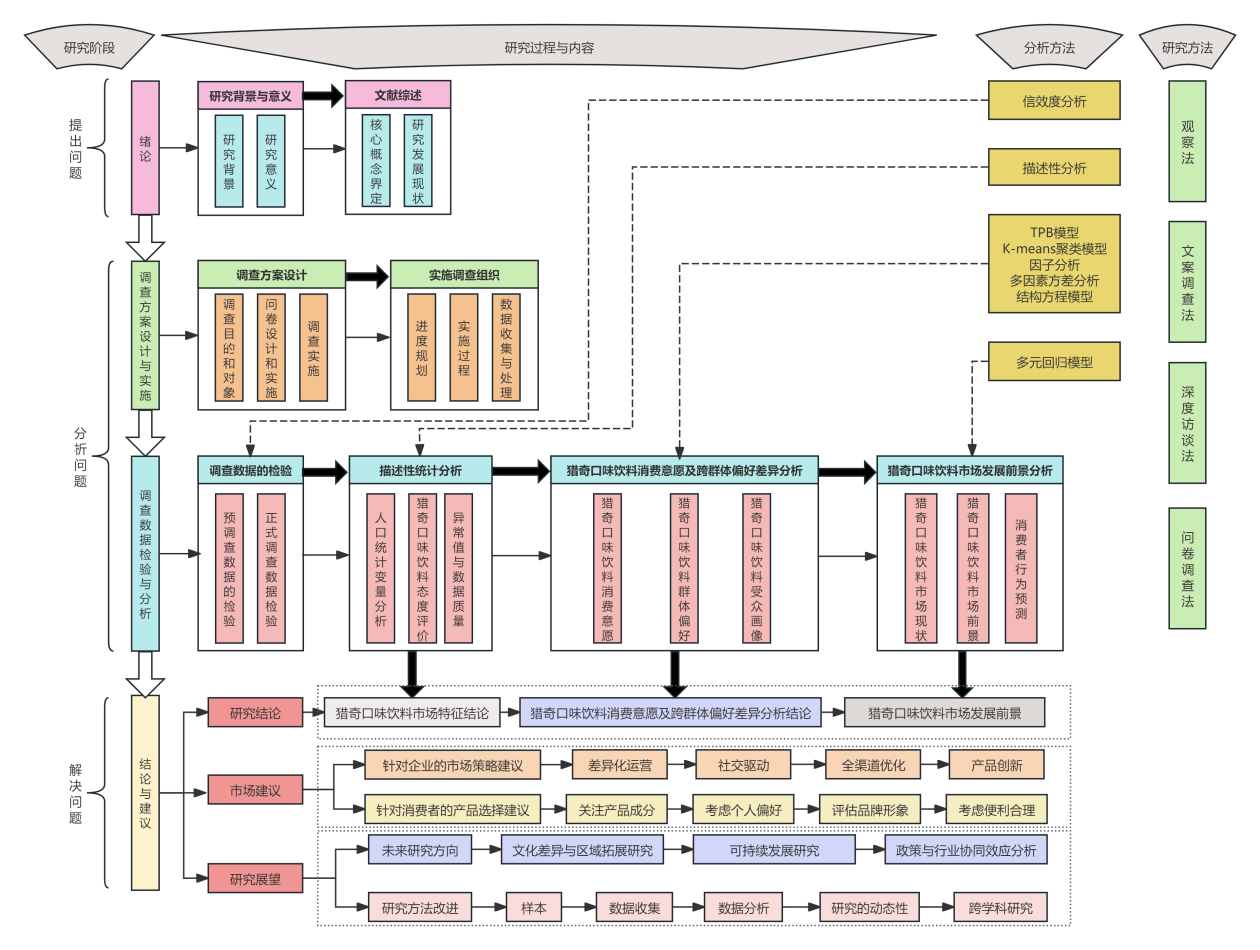
TPB concept diagram — original figure from the paper